More financial breathing room might mean covering a repair, taking time for a course or having a little more choice about work and care. Begin with what you want to make possible, rather than a promise to become completely independent of every obligation.
Housing costs, income, disability, caring responsibilities and unexpected expenses can limit your options. Spending decisions matter, but a shortfall is not automatically evidence that you have bought too many luxuries. Look at the situation you actually have and the support it may need.
On this page
Name the choice you want
Choose an aim you can describe: cover an annual bill without a scramble, reduce an optional monthly cost or understand what a change in working hours would involve. “Have more freedom” becomes easier to consider when you know what you want more room for.
Ask what would need to be in place. A change in work might involve income, transport, childcare, benefits or support from someone else. Gathering that information can be a useful first step before making a commitment.
You do not need to decide your whole future today. Separate the question you can investigate now from decisions that require more time or specialist advice.
Make a realistic money picture
Choose a way to record income and spending that you can use comfortably: paper, a spreadsheet or a tool you already have. Include regular commitments and less frequent costs, rather than only the expenses you wish were there.
The Consumer Financial Protection Bureau’s guide to assessing spending suggests looking at actual records and accounting for expenses that do not arise every month. Although written for people considering a home purchase, those steps can help you build a clearer starting picture.
Keep the review descriptive. If essential costs are greater than the money available, identifying that gap matters. A neater budget alone cannot create income that is missing.
Review one commitment at a time
Choose a cost you can reasonably reconsider. Is it still useful? What does cancelling or changing it involve? Would a cheaper option create another difficulty, such as losing accessible transport or necessary support?
Consider the whole trade-off before deciding. A small convenience can have value when time, energy or mobility is limited. You do not need to remove every enjoyable purchase to make a thoughtful choice about one commitment.
If costs are shared, discuss a specific proposal: “Could we choose a less expensive outing this month?” or “Can we review which subscriptions we both use?” Leave room for each person’s needs rather than making assumptions about what they should give up.
Clarify debt questions before choosing a plan
Gather the information you need about an obligation: the amount, due date, charges, interest and any terms you do not understand. Keep account details private when asking someone to help you organise the information.
If you may miss a payment, contact the provider through a verified channel to ask what options are available. Ask how a proposed arrangement affects the balance, fees and future payments, and request the terms in writing. An offer of flexibility needs checking rather than an assumption that there will be no consequences.
When several obligations compete or a decision affects housing, essential services or legal rights, consider qualified local debt or financial advice before choosing an order of action. Check a service’s credentials, costs and terms; be cautious about promises to erase every debt or pressure to pay immediately.
Let saving fit your circumstances
If there is room to set money aside, choose an amount and a purpose that fit the current picture. A fixed percentage is not a requirement you must meet to be responsible.
Consider when bills fall due before moving money automatically. Review the amount if income changes or an essential cost appears. Using money you saved for the need you planned for does not make the effort pointless.
If there is no spare money, focus on the support or information the shortfall calls for. You may need help checking eligibility for local assistance, understanding a bill or considering options with a qualified adviser.
Make room for choices that cost little
Some room can come from a clearer agreement about time: sharing a task, declining an optional commitment or protecting a short period for something you value. These changes may need cooperation, and they do not remove financial pressures.
Giving time or money can be meaningful if you want to and can afford it. It is not a condition for deserving stability, and you can decline a request that would leave an essential need unmet.
Choose one next action: list a less frequent expense, check a cancellation term, ask a provider a question or arrange advice. Review what you learned before taking the next step.
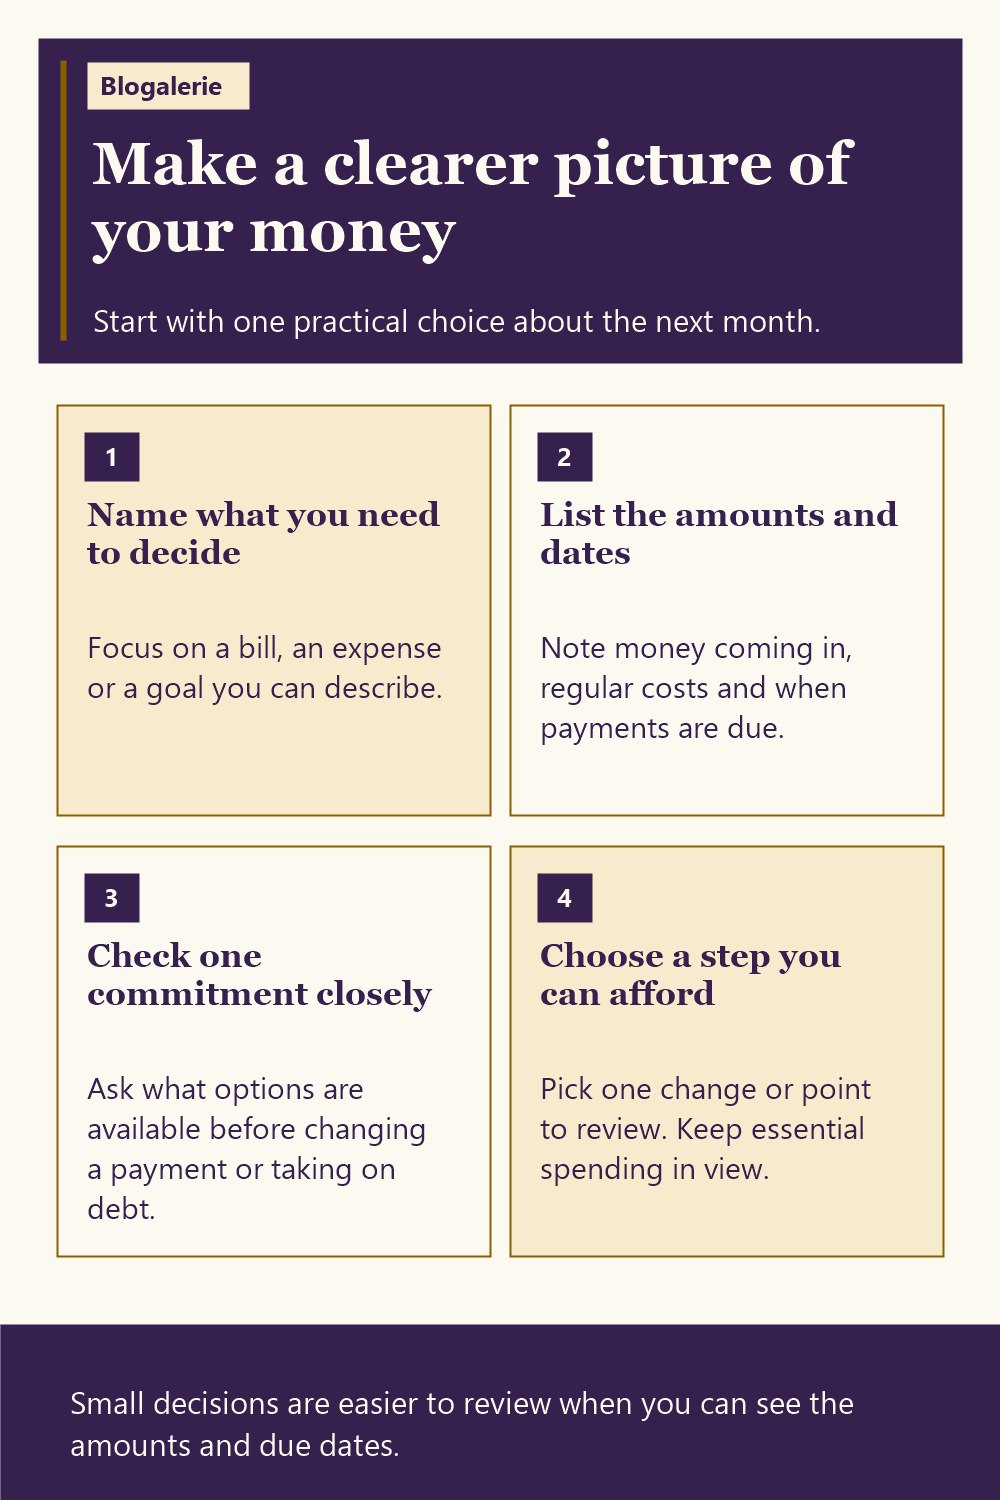
Read the infographic in text
Make a clearer picture of your money Start with one practical choice about the next month.
- Name what you need to decide Focus on a bill, an expense or a goal you can describe.
- List the amounts and dates Note money coming in, regular costs and when payments are due.
- Check one commitment closely Ask what options are available before changing a payment or taking on debt.
- Choose a step you can afford Pick one change or point to review. Keep essential spending in view.
Small decisions are easier to review when you can see the amounts and due dates.
‘Indentured servitude’ as described here evokes important considerations regarding personal freedom amidst consumer pressure today. This piece effectively underscores how one’s pursuit for stability can morph into self-imposed constraints fueled by debt obligations stemming from consumer habits ingrained within our society since youth—an alarming realization indeed! Encouraging self-reflection through suggested methods serves as an excellent starting point toward liberating oneself from such burdens; yet it begs further inquiry: What collective actions must we take as a society if we genuinely aim at diminishing these imposed limitations?
This article presents an intriguing perspective on consumerism as a form of modern indentured servitude. The assertion that financial obligations can bind individuals in ways reminiscent of historical servitude is thought-provoking. It challenges readers to reassess their relationship with money and material possessions critically. Furthermore, the five strategies proposed offer a pragmatic approach to reclaiming personal agency over one’s finances and lifestyle choices. However, I am curious about the effectiveness of these methods across different demographics and economic conditions. How might socioeconomic status influence one’s ability to implement such changes successfully? This complexity warrants further exploration.
The exploration of consumerism framed as a modern iteration of indentured servitude captures an essential critique of our current economic systems well. It highlights how individuals often trade autonomy for material goods or perceived security, ultimately leading them into cycles of relentless labor just to keep up with debts incurred through consumerist tendencies. Implementing the suggested strategies could potentially empower individuals; however, they may also require more profound changes in mindset influenced by cultural narratives around success and happiness tied closely with ownership and wealth accumulation.
‘Indentured servitude’ may seem like an archaic concept; however, its relevance resurfaces poignantly when considering today’s economic landscape laden with credit dependencies—an unsettling truth indeed! The article offers insightful strategies aimed at curbing excessive consumerism while promoting sustainable living practices; nonetheless, I am intrigued about potential psychological barriers people might face when attempting this shift towards frugality amidst societal expectations favoring material acquisition instead.
“The parallels between past forms of labor exploitation and contemporary financial entrapment provide significant food for thought regarding autonomy versus obligation in modern life scenarios today.” The strategies outlined do indeed present practical tools for navigating away from this ‘consumerism merry-go-round.’ Yet my thoughts drift toward larger questions: How do cultural values shape our understanding of needs versus wants? What role does education play in equipping individuals with skills necessary for making informed decisions regarding spending habits? Such inquiries would enhance discussions surrounding this topic significantly.
I find the historical context presented here rather enlightening. The transition from indentured servitude to modern-day credit dependence illuminates an insidious aspect of capitalism that many overlook. It is fascinating how societal norms around consumption have evolved while maintaining underlying exploitative dynamics. The suggestions offered for breaking free from this cycle are practical; however, they require a paradigm shift in how we perceive wealth and necessity. Such changes necessitate not only individual commitment but also systemic shifts in economic policies that promote sustainable living over perpetual consumption. I wonder how various communities might adapt these strategies within their unique socio-economic contexts.
The analogy drawn between past indentured servants and today’s debt-laden individuals is quite striking, yet it resonates deeply with contemporary experiences in consumer culture. Many people find themselves trapped in cycles of debt due to societal pressures to maintain certain standards of living which often leads to diminished quality of life overall. While I appreciate the five actionable steps provided for breaking free from this cycle, I believe it’s crucial to also address systemic issues at play such as income inequality and access to financial education resources which are essential for implementing meaningful change on a broader scale.
The historical comparison of indentured servitude to modern consumerism is quite compelling. It draws a parallel that many may not consider when examining the contemporary work-life balance. The notion that we can become enslaved to our financial obligations, albeit temporarily, raises significant questions about personal agency and freedom. While the article posits actionable steps towards financial independence, it also invites reflection on broader societal structures that perpetuate such conditions. Are we not also complicit in our own servitude by continually engaging with a consumerist culture? This piece certainly adds depth to the discussion about financial literacy and the importance of evaluating our lifestyle choices.